The vast majority of academic quantitative papers and emerging manager pitch decks evaluate strategy performance on historical midpoint 1-minute or daily OHLC bars. In institutional reality, midpoint backtests are mathematically disconnected from exchange physics. When an algorithmic strategy interacts with real-world matching engines, it encounters finite order book depth, First-In-First-Out (FIFO) queue priority, aggressive market impact, and severe adverse selection. This monograph dissects why strategies demonstrating paper Sharpe ratios of 3.0+ routinely suffer immediate capital decay upon live staging, and formalizes the discrete Level-3 order book simulation required to certify institutional execution viability.
1. The Midpoint Bar Illusion
A standard candlestick bar records four numbers: Open, High, Low, and Close. Typical backtesting frameworks evaluate strategy entry and exit by checking whether the bar's High was greater than the limit price, or by executing market orders at the bar Close.
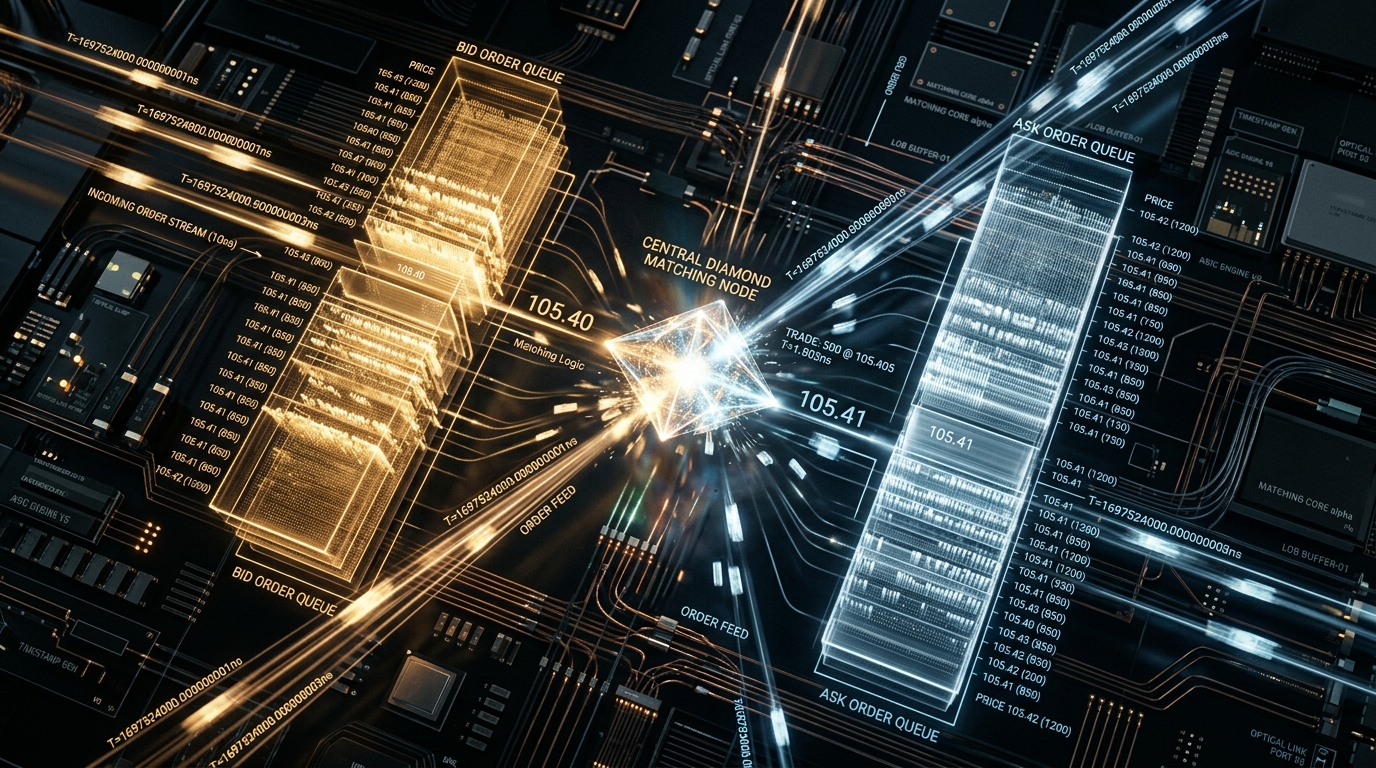
This simplification conceals a fatal flaw: it assumes that liquidity at the midpoint was infinitely deep, costless, and patiently awaiting the strategy's order. In listed exchange-traded futures (e.g., CME E-mini, 10-Year Treasuries) or Tier-1 FX, liquidity is a finite queue governed by strict temporal priority:
If price touches a limit level and immediately bounces, resting orders at the back of the queue receive zero fills. Backtests that assume complete execution on price touch overstate strategy win rates by up to 40%.
2. The Adverse Selection Trap: The Winner's Curse of Passive Limits
Why not simply execute passive limit orders to capture the bid-ask spread? In theoretical models, market making appears riskless. In live execution, passive limits suffer from severe adverse selection:
- When the market is about to reverse: Informed institutional traders consume the other side of the book, leaving your passive order unfilled. You miss the profitable trend.
- When the market is about to break out: Toxic flow violently sweeps the book, filling your resting order immediately before driving price through your position. You absorb the full loss.
3. The Five Microstructure Failure Vectors
Before approving allocations to high-turnover systematic strategies, diligence teams must audit these five microstructural leakage vectors:
The Midpoint Price Illusion
Simulating executions at (bid + ask) / 2 assumes the strategy can effortlessly cross the spread with zero price penalty. In reality, aggressive orders pay the full half-spread, and passive limit orders suffer adverse selection whenever filled.
FIFO Queue Position Depletion
In exchange matching engines (e.g., CME Globex), orders join the back of the queue at each price level. A backtest assuming immediate fill when price touches its limit price fabricates liquidity that was never allocated.
Adverse Selection Bias
Passive orders are disproportionately filled when toxic, informed flow is driving price through the level, and left unfilled when the market moves favorably. Midpoint backtests ignore this structural asymmetry.
Market Impact & Liquidity Elasticity
Large orders do not merely consume resting book depth; they alert predatory algorithms who cancel resting quotes and front-run parent slices across related derivatives and ETF baskets.
Unaccounted Exchange Tariffs & Clearing Fees
In high-turnover systematic strategies, exchange matching fees, NFA dues, clearing fees, and broker ticket charges consume 30% to 60% of gross paper alpha, turning flattering backtests into live cash bleed.
4. Institutional Remediation: Discrete Level-3 Blitz Verification
To guarantee live execution fidelity, Qlumina strategies are tested through the Blitz microstructure simulator:
- Direct Level-3 Order Book Reconstruction: Every individual exchange packet (adds, modifies, cancels, fills) is replayed bit-for-bit with nanosecond matching engine clock accuracy.
- Conservative Queue Modeling: Simulated limit orders are placed at the exact mathematical end of the queue. Fills require genuine volume depletion through the level plus a conservative cancellation buffer.
- Full Structural Fee Surcharge: Every backtest deducts exchange clearing fees, NFA/regulatory dues, broker ticket commissions, and overnight financing rates at Tier-1 prime broker rates (Clear Street schedules).
5. Institutional Due Diligence: 5 Questions for Allocators
Allocators evaluating algorithmic desks must require verifiable answers to the following 5 execution microstructure questions:
Institutional Synthesis: Grounding Alpha in Exchange Physics
Mathematical alpha on paper is worthless if it cannot survive the physical friction of exchange matching engines. Midpoint backtesting fabricates non-existent liquidity and ignores the severe adverse selection inherent in passive order queues.
By enforcing discrete Level-3 order book replay, FIFO queue priority modeling, and non-linear market impact penalties inside the compiled C++ Blitz engine, Qlumina guarantees that certified systematic strategies generate live cash flows rather than paper illusions.
Inspect Our Real-World Fill Slippage Ledgers
Institutional allocators and execution committees can audit live FIX order execution timestamps, fill slippage distributions, and fee transparency schedules within our secure institutional data room.