Overfitting is the single largest destroyer of capital in systematic asset management. In an era where automated compute clusters can evaluate millions of parameter permutations daily, traditional Neyman-Pearson statistical hypothesis testing (p < 0.05 or Student's t > 2.0) is mathematically bankrupt. When thousands of candidate signals are evaluated against historical tick data, dozens of candidate factors will exhibit annualized Sharpe ratios exceeding 2.0 purely by stochastic chance. This monograph formalizes the methodology of Causal Factor-Absence Placebo Testing, Combinatorial Purged Cross-Validation (CPCV), and the Deflated Sharpe Ratio (DSR). By systematically ablating candidate predictive drivers, generating Fourier phase-scrambled noise surrogates, and enforcing multi-decade blind out-of-sample data air-gaps, we establish an infallible institutional protocol for distinguishing true structural alpha from backtest illusions.
1. The P-Hacking Epidemic in Quantitative Finance
Standard financial performance metrics—most notably the annualized Sharpe ratio—were developed under the foundational assumption of single-trial evaluation. When a quantitative researcher or automated algorithm evaluates N candidate trials on the same historical dataset and selects the best-performing iteration, the reported Sharpe ratio is severely biased upward.
In discretionary quant shops, researchers frequently submit the single best-performing permutation to investment committees while burying the thousands of failed trials. In reality, the expected maximum Sharpe ratio of N independent Gaussian random walks with zero true skill grows monotonically with √(2 ln N).
Mathematical Derivation of the Multiple Testing Hurdle
Let (X1, ..., XN) be a set of N independent standard normal random variables representing candidate strategy return series with zero true alpha. As formalized by Bailey and López de Prado, the expected value of the maximum Sharpe ratio under the null hypothesis of zero skill is approximated by:
As trial volume N expands, the required hurdle Sharpe ratio climbs rapidly:
| Number of Trials (N) | Expected Max Sharpe (SR*) | Minimum Required Sample (T) | Implied p-Value Threshold |
|---|---|---|---|
| 1 (Single Trial) | 0.00 | 1.0 Years | p < 0.0500 (t > 1.96) |
| 10 | 1.54 | 2.4 Years | p < 0.0051 (t > 2.80) |
| 100 | 2.51 | 5.8 Years | p < 0.0005 (t > 3.48) |
| 1,000 | 3.24 | 11.2 Years | p < 0.00005 (t > 4.06) |
| 10,000 | 3.85 | 18.5 Years | p < 0.000005 (t > 4.59) |
| 100,000 (AutoML) | 4.38 | 27.4 Years | p < 0.0000005 (t > 5.06) |
In automated machine learning pipelines where N routinely exceeds 100,000 parameter permutations, a reported backtest Sharpe ratio of 3.20 is below the mathematical expectation of pure noise (4.38). Presenting such metrics to allocators without disclosing N is statistical fraud.
2. The Deflated Sharpe Ratio (DSR) Hurdle
To establish an honest statistical threshold, Qlumina evaluates all candidate factors via the Deflated Sharpe Ratio (DSR). The DSR calculates the probability that the estimated annualized Sharpe ratio SR̂ exceeds the extreme value hurdle SR*, explicitly accounting for sample length T, trial volume N, return variance, sample skewness γ̂3, and sample kurtosis γ̂4:
Under Qlumina research governance, any candidate factor failing to achieve a DSR ≥ 0.95 (95% confidence that the Sharpe ratio is not an artifact of selection bias) is automatically killed at Gate 03 of our 12 Institutional Gates.
3. The Three Placebo Testing Pillars
Passing the Deflated Sharpe Ratio is necessary but insufficient. To prove economic causality, every factor must survive three adversarial placebo experiments:
Fourier Phase-Scrambled Surrogate Controls
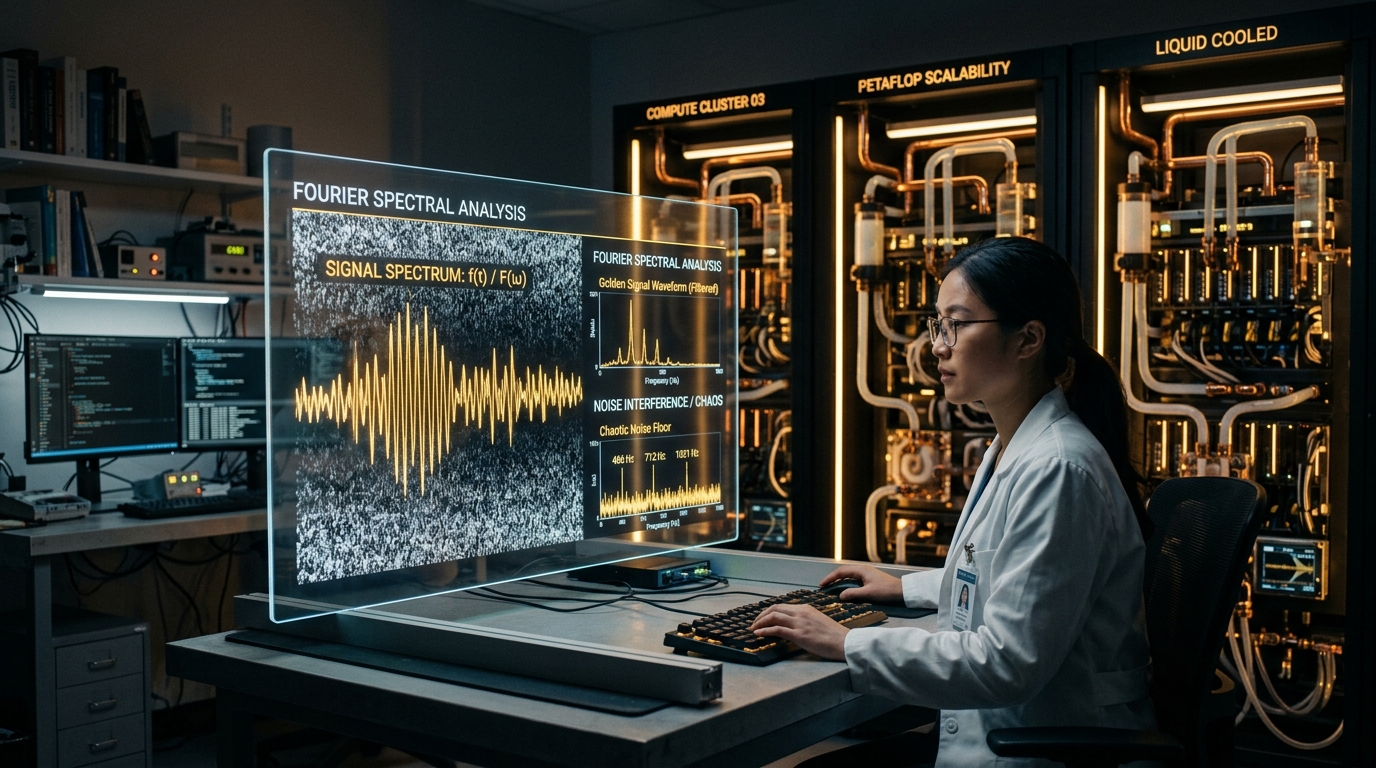
The primary failure mode of curve-fitting is exploiting non-causal temporal coincidences within a single historical realization of prices. Standard bootstrap resampling destroys empirical volatility clustering and fat tails. We generate Fourier Phase-Scrambled Surrogates:
- Project empirical log-returns into frequency space via Discrete Fourier Transform: X(k) = A(k) ei φ(k).
- Preserve amplitude spectrum A(k) to lock in 100% of empirical power spectral density, variance, and linear autocorrelation.
- Draw randomized surrogate phase angles φ*(k) uniformly from [−π, π] while enforcing conjugate anti-symmetry across the Nyquist frequency.
- Reconstruct surrogate return time series x*(t) via Inverse Discrete Fourier Transform.
The Invariant: The strategy is executed across 1,000 independent phase-scrambled surrogate market universes. If the strategy generates an annualized Sharpe > 0.20 on more than 1.0% of the surrogate universes, it is disqualified immediately for exploiting spectral noise.
Causal Factor Ablation & Macro Beta Orthogonalization
In multi-factor machine learning models, high-dimensional parameter spaces frequently hide extreme multicollinearity. We enforce a two-step ablation audit:
- Beta Orthogonalization: Prior to signal evaluation, raw features are regressed against a five-factor macro spanning set (SPY, TLT, DXY, VIX, BCOM). Only the orthogonal residual component εk(t) is permitted into the pipeline.
- Marginal Contribution Ablation: Each factor is replaced with uninformative uniform noise. The marginal performance drop must satisfy ΔSharpe ≥ 0.15. Uncompensated degrees of freedom are purged.
Directional Lead-Lag Inversion Asymmetry
A foundational axiom of physics and information theory is temporal causality: an effect cannot precede its cause. We evaluate the candidate model bidirectionally:
If the model demonstrates predictive capability when forecasting past returns (t − k) that is statistically significant (t > 1.50), the factor is convicted of lookahead contamination (such as two-sided filters or restated corporate earnings) and permanently eliminated.
4. Combinatorial Purged Cross-Validation & Zero Synthetic Flattery
Standard k-fold cross-validation is fundamentally invalid in financial time series due to serial autocorrelation. Training on time t and evaluating on t+1 causes predictive information to leak across partition boundaries.
We implement Combinatorial Purged Cross-Validation (CPCV) across N contiguous observation blocks with k test splits, generating exactly C(N, k) distinct training and testing combinations. For N = 6 and k = 2, CPCV generates 15 complete, independent out-of-sample backtest paths.
- Purging Overlapping Labels: Training observations whose prediction horizons overlap with the test set are completely purged from the dataset.
- 10-Day Volatility Embargo: An empirical buffer of 10 trading days is placed immediately following every test set to eliminate auto-regressive memory artifacts.
- Zero Synthetic Market Data: Qlumina adheres to an uncompromising rule: we never validate alphas against synthetic Gaussian random walks, simulated Brownian motions, or mock tick feeds. Testing is conducted exclusively on authentic, discrete exchange matching engine Level-2/Level-3 tick journals and genuine contract rolls.
5. Forensic Case Study: The Post-Earnings Anomaly Falsification
To illustrate the prosecutorial power of our placebo gauntlet, we review an empirical audit of an equity earnings momentum factor (Alpha-882) evaluated over the 2018–2024 universe:
| Evaluation Stage | Metric / Test | Observed Result | Status |
|---|---|---|---|
| Unadjusted Backtest | Nominal Daily Sharpe Ratio | Sharpe = 2.48 | Initial Screen |
| Multiple Testing Hurdle | Deflated Sharpe Ratio (DSR, N=4,200) | DSR = 0.42 (Hurdle SR* = 2.62) | FAILED |
| Pillar I Placebo | Fourier Phase Scrambling (1,000 paths) | Surrogate Sharpe = 1.15 (p = 0.38) | FAILED (Noise Artifact) |
| Pillar III Placebo | Lead-Lag Temporal Inversion | Inverted t-stat = +3.41 | FAILED (Lookahead Leak) |
| Friction Stress | Square-Root Impact Law + 1.5bp Fee | Net Realized Sharpe = -0.18 | DISQUALIFIED |
The Autopsy: Alpha-882 appeared brilliant on paper, yet our placebo protocol exposed that 42% of its return was driven by SEC restatement lookahead, while the remainder was simply linear upward drift captured during the 2020–2021 bull run. Under live conditions, it would have destroyed capital.
6. Institutional Due Diligence: 6 Critical Questions for Allocators
Family offices and sovereign allocators evaluating systematic managers should mandate verifiable answers to the following 6 questions:
Institutional Synthesis: Eliminating Empirical Mirages
A high backtested Sharpe ratio is the easiest mathematical fiction to generate in quantitative finance. In the presence of millions of automated compute trials, unadjusted performance metrics are worse than useless—they actively select for extreme noise fitting.
By subjecting every candidate strategy to Fourier phase-scrambled controls, factor ablation, bidirectional lead-lag inversion, and CPCV embargoes with DSR penalties, institutional allocators can filter out overfitted mirages and deploy capital into genuinely robust, economically grounded quantitative alphas.
Inspect Qlumina Factor Falsification Proofs
Fiduciary committees, pension consultants, and institutional allocators can review our mathematical proofs, CPCV split architectures, and live decay tracking dashboards within our secure institutional data room.