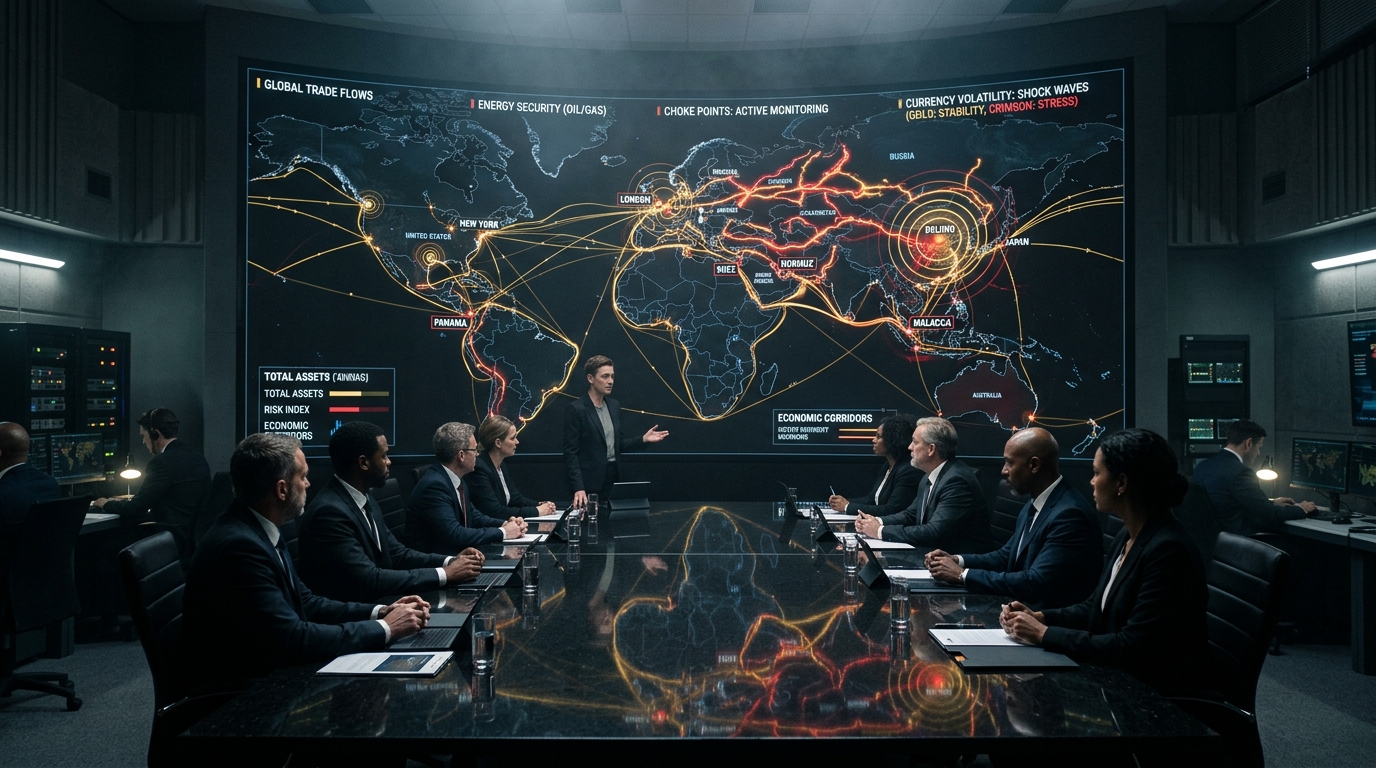
Geopolitical conflict is not an emotional tragedy for a quantitative system—it is a non-linear data event. While discretionary managers freeze under the psychological burden of war headlines, systematic models act as liquidity providers of last resort, monetizing volatility spikes and trading the statistical reverberations across global supply chains.
The Permacrisis Landscape: The Fog of War
As institutional allocators navigate 2026, the global financial landscape is characterized by perpetual friction: regional conflicts across Eastern Europe and the Middle East, maritime trade choke-point disruptions, strategic commodity embargoes, and shifting currency alignments.
For discretionary portfolio managers, these macro disruptions constitute a paralyzing “Fog of War.” Human decision-makers are flooded with contradictory news, government communiqués, and social media propaganda. The instinct is almost universally to freeze, hedge haphazardly at peak implied volatility, or liquidate assets at the exact bottom of market distress.
Quantitative systems do not experience panic. They recognize that geopolitical shocks alter two specific variables: the price of liquidity and the dispersion between correlated assets. By replacing emotional deliberation with high-frequency statistical logic, systematic strategies transform macro chaos into repeatable alpha.
The Speed Gap: Headlines vs. Order Books
The fundamental flaw of discretionary macro trading in modern markets is latency. In an era of algorithmically coordinated global markets, by the time a breaking news bulletin hits a terminal screen, the liquidity window has already slammed shut.
Systematic models do not wait for the news; they monitor the microstructure of the market that precedes and absorbs it:
01. Order-Book Depletion
Algorithms detect subtle institutional quote cancellations and bid/ask book thinning seconds before breaking announcements hit public wires.
02. Machine-Speed NLP
Natural Language Processing engines digest localized foreign-language press releases and emergency defense communiqués in milliseconds, pricing risk instantly.
03. Physical Telemetry
Satellite transponders, maritime tanker rerouting feeds, and pipeline pressure telemetry feed real-time logistical context directly into alpha engines.
Mapping Non-Linear Feedback Loops
Modern geopolitical flashpoints do not stay confined to their geographic borders. A disruption in the Persian Gulf or Red Sea triggers instantaneous, non-linear ripple effects across dry bulk freight, European natural gas, East Asian semiconductor fabrication, and sovereign credit default swaps.
Quantitative systems deploy multi-factor correlation matrices to harvest alpha across the indirect “proxy channels” where crowded retail money cannot execute:
The Psychological Moat: Eradicating Cognitive Bias
The greatest threat to capital preservation during international conflict is human cognitive frailty. Discretionary managers routinely fall victim to three destructive psychological traps:
Patriotic Bias
Overweighting domestic assets or holding losing positions out of misguided national loyalty when empirical metrics dictate defensive rebalancing.
Price Anchoring
Refusing to buy crude oil above $110 or sell sovereign debt at new yield highs because historical peacetime benchmarks distort current structural realities.
Paralysis by Analysis
Hesitating to rebalance while waiting for clarity from political leaders—allowing initial 3% drawdowns to metastasize into catastrophic 25% portfolio impairments.
Historical Case Studies of the “Alchemists”
Throughout modern market history, the greatest institutional wealth transfers have occurred when systematic quants and tail-risk specialists capitalized on the emotional panic of discretionary allocators:
The 2008 Financial Crisis: The Quant Renaissance
+80% Net ReturnWhile the S&P 500 plummeted 38.5% and the average hedge fund lost nearly 20%, Jim Simons' Renaissance Medallion Fund generated an astonishing 80% net return, while Brevan Howard posted +19% by harvesting extreme volatility across foreign exchange and rate term structures.
The March 2020 Pandemic Shock: Asymmetric Tail Convexity
+4,144% Q1 ReturnDuring the acute liquidity crash of March 2020, Universa Investments delivered a historic +4,144% return on its dedicated tail-risk mandate. By methodically risking a fraction of basis points on deep out-of-the-money convexity, systematic insurance completely insulated LP balance sheets.
The 2022 Energy Shock: Multi-Strat Supremacy
$16B Record ProfitAs the Ukraine conflict triggered historic volatility in European gas, crude, and agricultural inputs, Ken Griffin's Citadel generated a record-breaking $16 billion net profit (+38.1%), demonstrating the insurmountable superiority of high-frequency systematic commodities execution.
Structural Security: Segregated Custody During Conflict
During geopolitical crises, brokerages fail, clearinghouses invoke emergency margin multipliers, and sovereign states freeze offshore assets. For family offices and institutional allocators, the vehicle structure is just as critical as the algorithm.
Under Qlumina's BVI Separately Managed Account framework, client capital is fully quarantined:
- Segregated Title: Assets remain in the investor's own legal entity at Tier-1 custodians, preventing co-mingled freeze contagion.
- Immediate De-Risking: In the event of systemic escalation, the allocator can unilaterally revoke trading permissions or sweep collateral to risk-free sovereign paper instantly.
Five Diligence Questions for Macro Allocators
When stress-testing a macro systematic manager, allocator diligence committees should examine these five operational invariants:
How does the system ingest geopolitical shocks before news reaches terminals?
Headline feeds are lagging indicators. Ask whether the manager monitors order-book depth depletion, cross-border currency basis shifts, and real-time maritime or commodity flow telemetry. By the time a headline flashes on Bloomberg, the alpha has already normalized.
What pre-committed risk controls govern overnight gap risk?
Geopolitical flashpoints frequently erupt outside standard market hours. Ask how the system handles weekend gap openings, liquidity air pockets, and circuit breakers. Systems must feature pre-hedged tail protection rather than relying on human committee meetings during market panics.
How are non-linear cross-asset feedback loops modeled?
A military escalation in the Strait of Hormuz is not simply an oil trade; it cascades into shipping insurance premiums, fertilizer input costs, agricultural futures, and semiconductor supply chains. Robust quantitative models harvest alpha across the indirect proxy channels where retail capital cannot follow.
How does the manager immunize the portfolio from human cognitive bias?
During acute international conflict, discretionary portfolio managers fall prey to emotional paralysis, patriotic bias, and anchoring. Ask how the firm enforces systematic discipline so that capital is allocated strictly based on statistical probability and risk-adjusted return.
Can investor capital be quarantined during global market freezes?
When major geopolitical shocks trigger exchange halts or sovereign capital controls, commingled offshore funds frequently suspend redemptions. In an institutional SMA, capital resides in the client's segregated prime account, allowing the allocator to protect or withdraw liquidity independently.
Conclusion: The Future of Defensive Alpha
In 2026, “defensive allocation” no longer means burying capital in physical gold or passive sovereign bonds with negative real yields. In a hyper-financialized, multipolar world, true defense requires agility, sub-second execution, and systematic emotional neutrality.
By engineering trading logic to embrace volatility rather than fear it, quantitative managers transform global macro conflict from a source of paralysis into an engine of durable, uncorrelated institutional alpha.
Discretionary capital consistently falters in geopolitical regimes due to newsflow latency, emotional anchoring, and unhedged basis slippage. Systematic mandates harvest positive expectancy by isolating non-linear transmission delays across proxy asset classes, maintaining pre-calibrated tail protection, and operating inside segregated custody architectures that eliminate counterparty and jurisdictional freezing risk.
Review Macro Strategy Track Records
Access certified monthly statements, drawdown duration curves, and microstructure execution telemetry across Qlumina's systematic mandates in our secure Data Room.