Artificial intelligence has changed how trading edges are discovered. It has not changed what makes them real — or who can find them. The honest answer to the question above is yes. But only briefly, only for a few, and only for those who understand why the presses keep jamming.
There is a peculiar asymmetry in how institutional capital is approaching AI-driven investing. On one side stand the true believers, for whom a neural network is a philosopher's stone — point it at a market, and it transmutes noise into gold. On the other stand the waiters: sophisticated allocators, family offices, and investment committees who have seen enough hype cycles — blockchain, big data, the cloud — to believe the prudent move is to let the technology mature and pick the winners later.
Both positions feel defensible. Both are wrong, and for the same reason: they treat AI as the subject of the sentence. It isn't. The subject is alpha — where it comes from, how fast it dies, and who has the scar tissue to tell a genuine edge from a curve-fit mirage. That judgment is not new. It is earned across decades of bull and bear markets, and it is available for evaluation today.
The questions are old. Only the answers are new. And the answers are perishable.
What AI Actually Changes — and What It Doesn't
To understand what AI does to investing, look at what compute did to chess. In 1997, Deep Blue beat Garry Kasparov. Pundits declared the end of human chess. What actually happened was more interesting: chess did not die; it accelerated. The openings became deeper, the preparation became sharper, and the players who used engines to test ideas — rather than outsource thinking — dominated the board. The engine did not eliminate human judgment; it raised the cost of not having it.
The same dynamic is playing out in quantitative research. What AI solves is the hypothesis generation bottleneck. A traditional research team might formulate and backtest twenty promising factor candidates in a month. An AI-augmented research pipeline can evaluate tens of thousands across multiple asset classes, time horizons, and structural regimes in days.
What AI does not solve is the physics of markets:
- Non-stationarity: Market regimes shift. A neural net trained on 2012–2021 knows everything about a world with zero rates and quantitative easing, and nothing about a world with 5% sovereign yields and geopolitical trade fractures.
- Reflexivity: The moment a trading edge is discovered and traded with sufficient volume, the market adapts. The act of extracting alpha destroys the alpha.
- Execution friction: An algorithm that shows a 4.0 Sharpe ratio on 1-minute close prices can evaporate entirely once crossed with the real-world costs of exchange fees, adverse selection, and bid-ask spreads.
The Driver, Not the Car
Formula One teams spend hundreds of millions of dollars building aerodynamic chassis, tuning hybrid power units, and analyzing telemetry down to the millisecond. Yet the driver in the cockpit still decides whether the machine wins or hits the barriers.
In quantitative asset management, AI is the vehicle; the portfolio manager is the driver. A brilliant model in the hands of an inexperienced engineer is an invitation to ruin. Without scar tissue earned from live drawdowns, an operator cannot distinguish between true structural alpha and an accidental polynomial curve-fit.
Most importantly, they know what strategy decay looks like in a live market, because they have watched strategies die. A backtest tells you a signal worked. Experience tells you why it worked — and therefore what will kill it. The crowding that slowly suffocates a factor. The regime shift that inverts a correlation overnight. The execution slippage that turns a paper edge into a live loss. This is knowledge that cannot be scraped or prompted into existence. It is accumulated one drawdown at a time.
The Flywheel: Recursive Self-Improvement
Here is where experience stops being an advantage and starts being a moat.
The most powerful quantitative teams are not training their models on raw market data — anyone can buy that. They are training on their own proprietary libraries of winning strategies: signals and trades that have already proven themselves profitable over the past decade or two, with real fills and real risk attached. And this unlocks the mechanism that separates the leaders from the field: recursive self-improvement. Models trained on a library of proven strategies generate new candidate strategies; the best of those survive live trading and join the library; the enlarged library trains the next generation of models. Each loop makes the next loop smarter. The system does not merely find edges — it learns what finding edges looks like.
There is precedent for the power of this loop. When DeepMind's AlphaZero mastered chess and Go, it did not study human games; it improved by playing against itself, and within hours surpassed a millennium of accumulated human knowledge. But markets are not chess. The rules shift mid-game, opponents adapt, and the board fights back. Self-improvement unconstrained by reality produces beautifully overfitted nonsense. That is why the anchor matters: in trading, recursive self-improvement is only as good as the proven, live-market strategies at its core.
The Physics of Alpha Decay
Academic finance has studied decay for decades, and the findings are consistent enough to be called laws. McLean and Pontiff examined roughly one hundred published stock-return anomalies and found the average one shrank by 58% after publication — not because the research was wrong, but because capital is a solvent: once an anomaly is known, money flows in and dissolves it. Recent work derives the functional form of the decay itself — hyperbolic, not linear — meaning edges collapse fastest precisely when they are newest and most crowded:
| Strategy Frequency | Underlying Mechanism | Expected Half-Life | Crowding Sensitivity |
|---|---|---|---|
| Low-Frequency | Economically grounded macro factors & value | Multi-Year (2 – 5 Years) | Low – Gradual Capital Absorption |
| Medium-Frequency | Statistical arbitrage, momentum, factor blends | 1 – 3 Years | Moderate – Systematic Factor Crowding |
| High-Frequency | Order-flow imbalances, intraday microstructure | 3 – 6 Months | Lethal – Millisecond Latency & Volume Bleed |
This yields an uncomfortable truth: in systematic investing, time is not neutral. A strategy's early months are its richest, because they precede the crowd. Renaissance Technologies' Medallion Fund, which has compounded at roughly 66% gross annually since 1988, has been closed to outside capital for decades. The lesson is not that Medallion was good. It is that the best capacity in this industry closes — permanently, and usually early.
What to Look For: Six Questions That Matter
If decay is the physics, due diligence is the engineering. Each question below descends from four decades of quantitative manager selection, sharpened for the AI era. A manager who answers all six crisply is worth your time. A manager who answers none is selling you a backtest.
Who is driving the car?
Before the models, the people. How many full market cycles has the team traded through — not backtested, traded? Do they have depth in the markets they trade — the seasonality of softs and meats, the volatility term structure of energy, the mechanics of the arbitrage they claim to harvest? Ask what killed their last strategy and how they knew. Veterans answer instantly and specifically. Everyone else answers vaguely and slowly.
Is there a flywheel — and what anchors it?
Ask whether the firm's models learn from a proprietary library of live, proven strategies, and how recursive self-improvement is constrained by real-world results. A flywheel anchored in twenty years of fills is a moat. A flywheel anchored in backtests is a centrifuge for overfitting.
What is your multiple-testing discipline?
An AI that tests ten thousand hypotheses will find hundreds that look brilliant by chance. Ask about out-of-sample protocols, walk-forward validation, and deflated Sharpe ratios. A Sharpe of 3 discovered on the first try means something. Discovered on the ten-thousandth try, almost nothing.
Where does the edge live — model or machine?
Models are replicable; infrastructure is not. Ask what fraction of returns survives contact with live execution: slippage assumptions, fill rates, transaction-cost analysis against real fills. The durable firms are plumbing companies with research labs attached.
What is the capacity, and how do you detect your own decay?
Every strategy has a dollar figure beyond which its own trading destroys its returns — honest managers state theirs and close. And live strategies should be monitored against their own training behavior, with pre-committed retirement rules. Kill-switches that require a committee meeting are ornaments, not controls.
Can you explain the edge in one sentence without saying 'AI'?
The best strategies rest on an intelligible economic rationale — a behavioral bias, a structural constraint, a flow that must transact regardless of price. Edges with a reason decay slower than edges with only a correlation.
Where the Drivers Go
For twenty years, the answer was simple: the multi-manager platforms. Millennium, Citadel, Balyasny, Point72. They offered capital, infrastructure, and data that no startup could match.
Today, that calculus is breaking down. Pass-through fees, non-competes, and IP ownership restrictions are driving premier quantitative researchers to spin out into independent architectures backed by turnkey prime clearing.
The Cost of Waiting
Waiting for the field to mature feels conservative. In systematic investing, it is an aggressive bet on missing the harvest.
When Renaissance closed Medallion in 1993, the allocators who had hesitated spent the next thirty years watching from the outside. Capacity in genuinely superior systematic strategies does not expand with popularity; it closes.
So — Can AI Print Money?
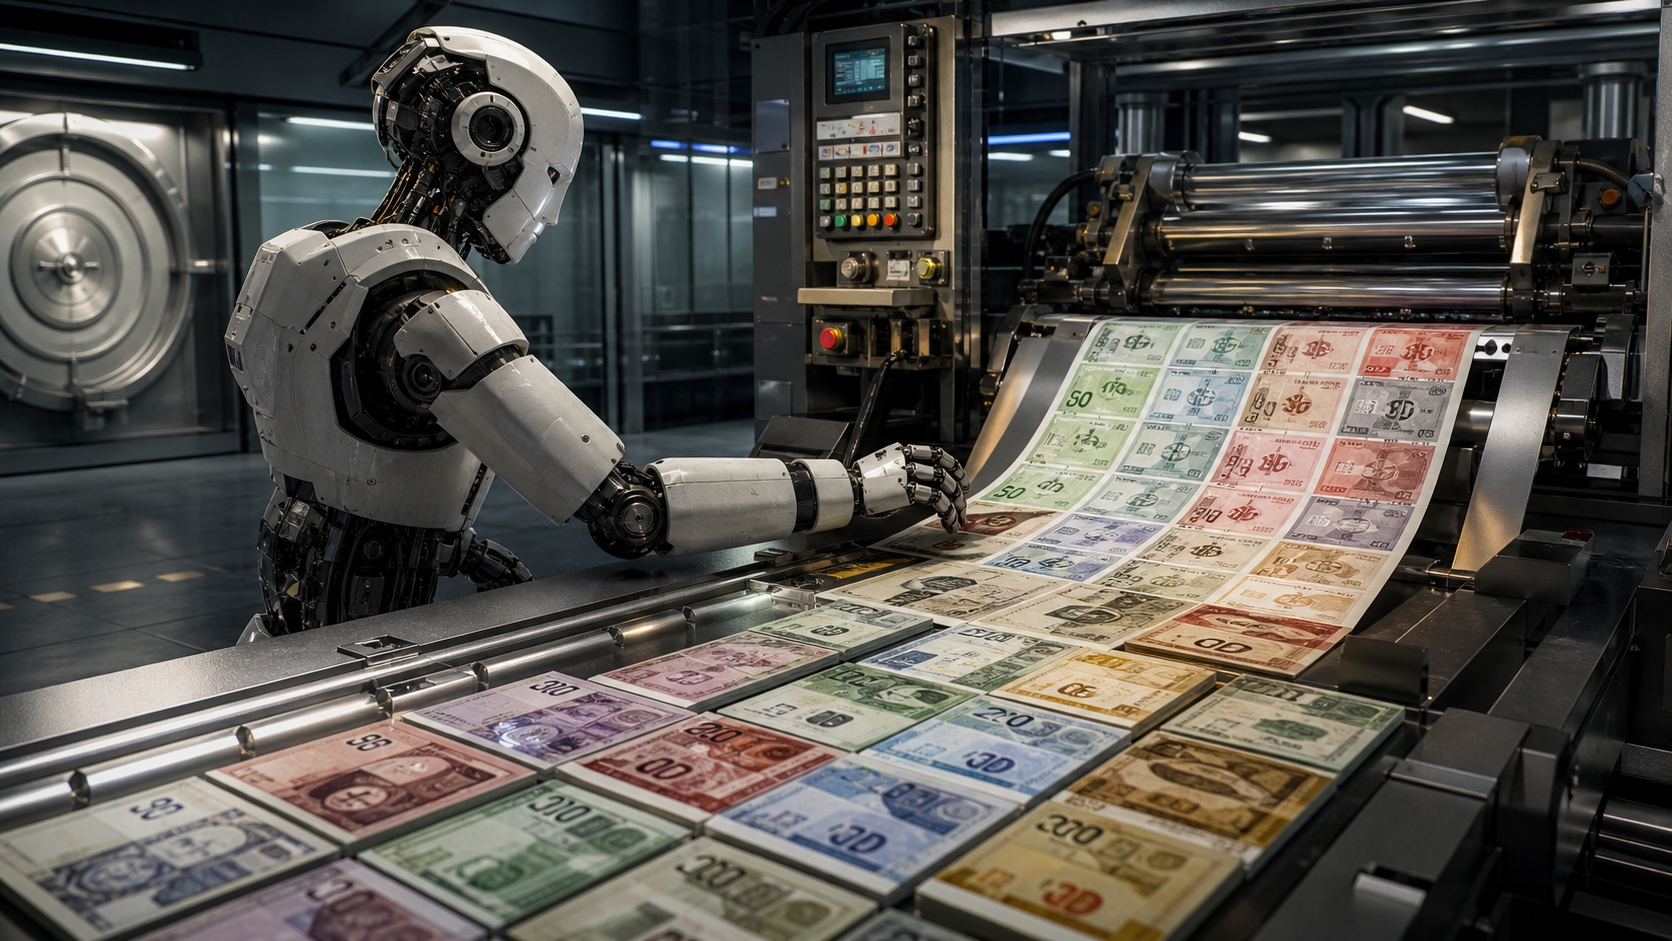
Yes. Briefly, and per edge. Every strategy is a printing plate: it runs hot, it degrades, and it is retired. The firms that endure are not the ones that found a single magical plate; they are the ones that built a mint — veteran judgment to design the plates, proven strategies to anchor the learning loop, infrastructure to run the presses, and the discipline to decommission each plate before it starts printing losses.
Institutional Synthesis: Building the Mint, Not the Plate
AI accelerates quantitative hypothesis generation by orders of magnitude, but market non-stationarity, reflexivity, and hyperbolic alpha decay remain unyielding laws of physics.
Durable institutional returns depend not on automated magic, but on veteran operational judgment, anchored recursive flywheels, strict capacity governance, and segregated SMA clearing rails.
Evaluate Qlumina's Quantitative Framework
To learn how Qlumina applies veteran-led strategy development, anchored self-improvement loops, capacity governance, and live decay monitoring across segregated SMA accounts — request access to our diligence data room.